
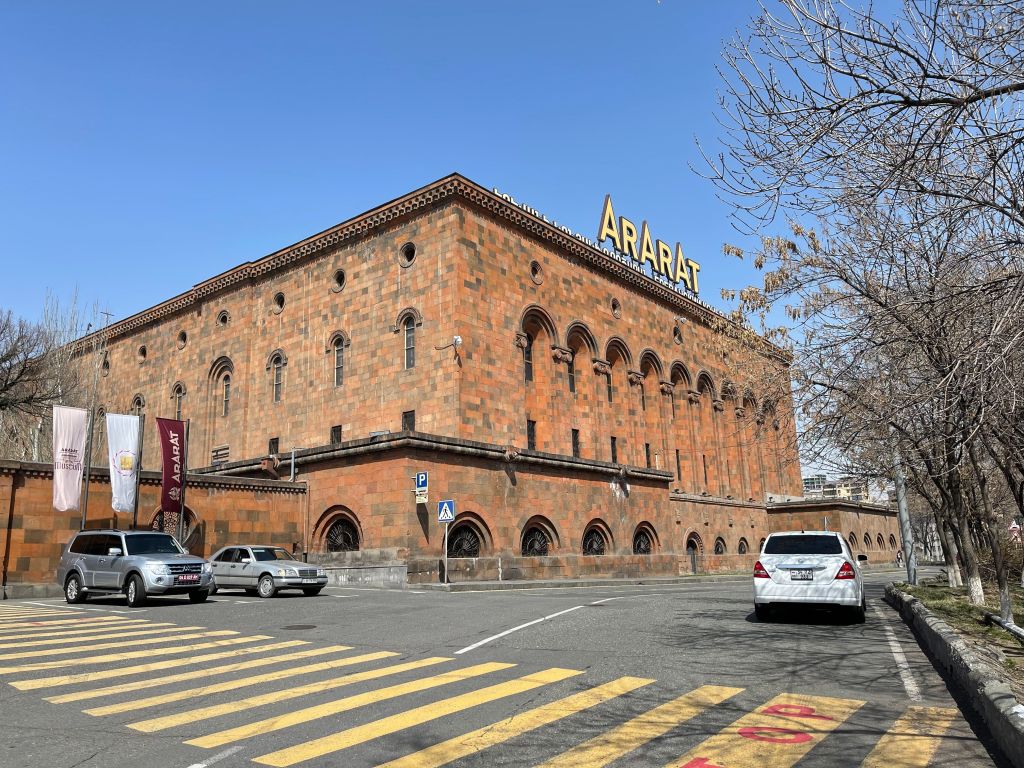
Real estate investment is never risk-free, and those risks can vary significantly from one part of the world to another.
Depending on the market, the main threat may come from demographic and economic trends, geopolitical instability, or political and institutional change. Each region therefore has its own vulnerabilities, which investors need to understand before committing capital.
These risks can broadly be grouped into three main categories, although they take different forms from one country and region to another.
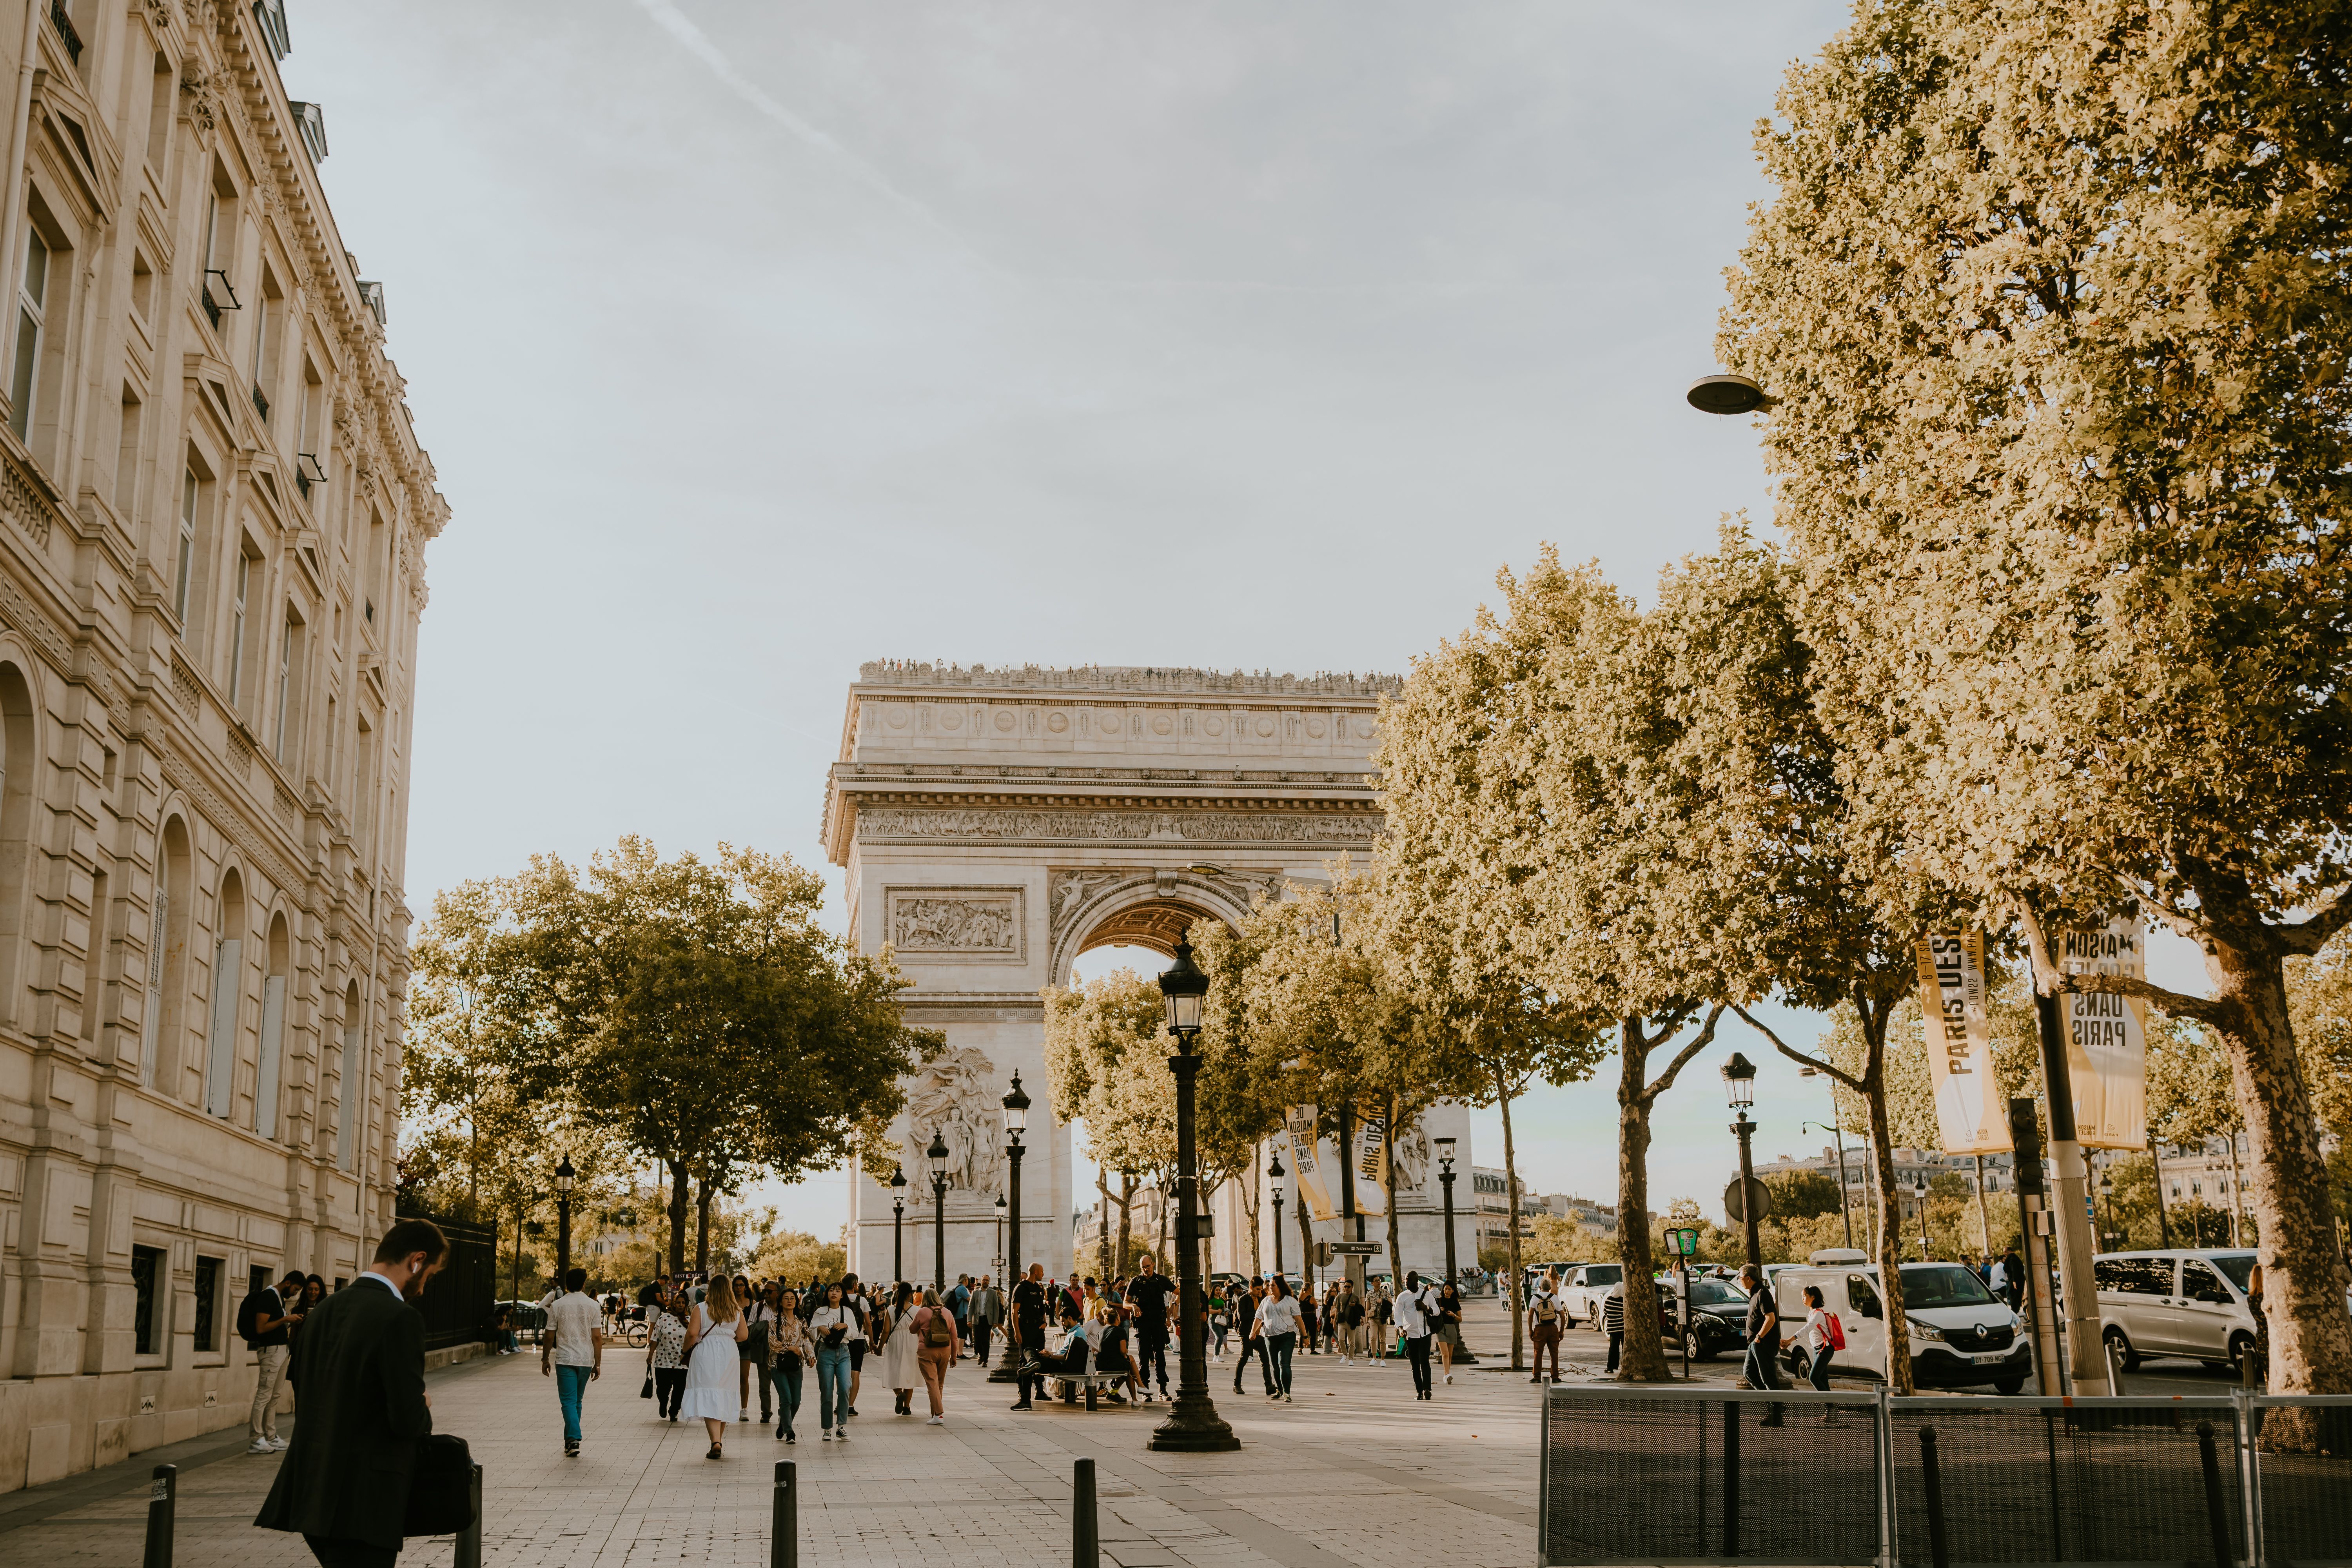
1. Western Europe: Stagnation and Concentration
The main real estate risk in Western Europe is probably not a sudden collapse.
It is a much slower process.
The risk comes from economic stagnation, population ageing, and the gradual concentration of people and wealth in a relatively small number of major cities and economically dynamic regions.
The euro area is currently experiencing a period of weak economic growth. Structural challenges include an ageing population and persistently low productivity growth.
This does not mean, of course, that the whole of Western Europe will lose population or become uniformly poorer.
The reality is much more geographical.
Some metropolitan areas continue to attract residents, capital, skilled migrants and businesses, while many smaller towns and rural areas are ageing and gradually losing population.
In some regions, long-term demographic decline can result in vacant housing, falling property values and a shrinking tax base with which to finance public services.
Two very different property markets can therefore exist within the same country
On one side are cities such as:
Paris, Geneva, Amsterdam, London, Milan, Munich, and other major university and metropolitan centres.
Population remains concentrated in these areas, land is scarce and housing demand remains strong.
On the other side are:
smaller towns and rural areas where demand for property is gradually declining.
The difference can become considerable.
Property values in major metropolitan areas can be far higher than those in smaller towns, and large urban areas have generally experienced much stronger price growth over the past decade.
In areas facing severe demographic decline, the problem is not necessarily the theoretical value of the property.
Sometimes, it is simply the absence of buyers.
A property may retain an official or advertised value while becoming extremely difficult to sell.
In extreme cases, when renovation, taxation and maintenance costs exceed realistic prospects for resale or rental income, the true economic value of a building can approach zero.
But major cities have their own risks
It might therefore seem logical simply to invest in the largest metropolitan areas.
Unfortunately, it is not quite that simple.
When housing demand becomes very strong and affordability turns into a political issue, governments tend to intervene more aggressively.
Rent controls, stronger tenant protections, restrictions on short-term rentals, energy-efficiency requirements, and additional taxes on second homes or vacant properties are making residential real estate increasingly regulated.
This creates an interesting paradox in Western Europe:
In declining regions, the risk is insufficient demand. In highly attractive regions, demand can become so strong that property returns themselves become a political issue.
For investors, the Western European risk is therefore largely one of location selection and regulation.
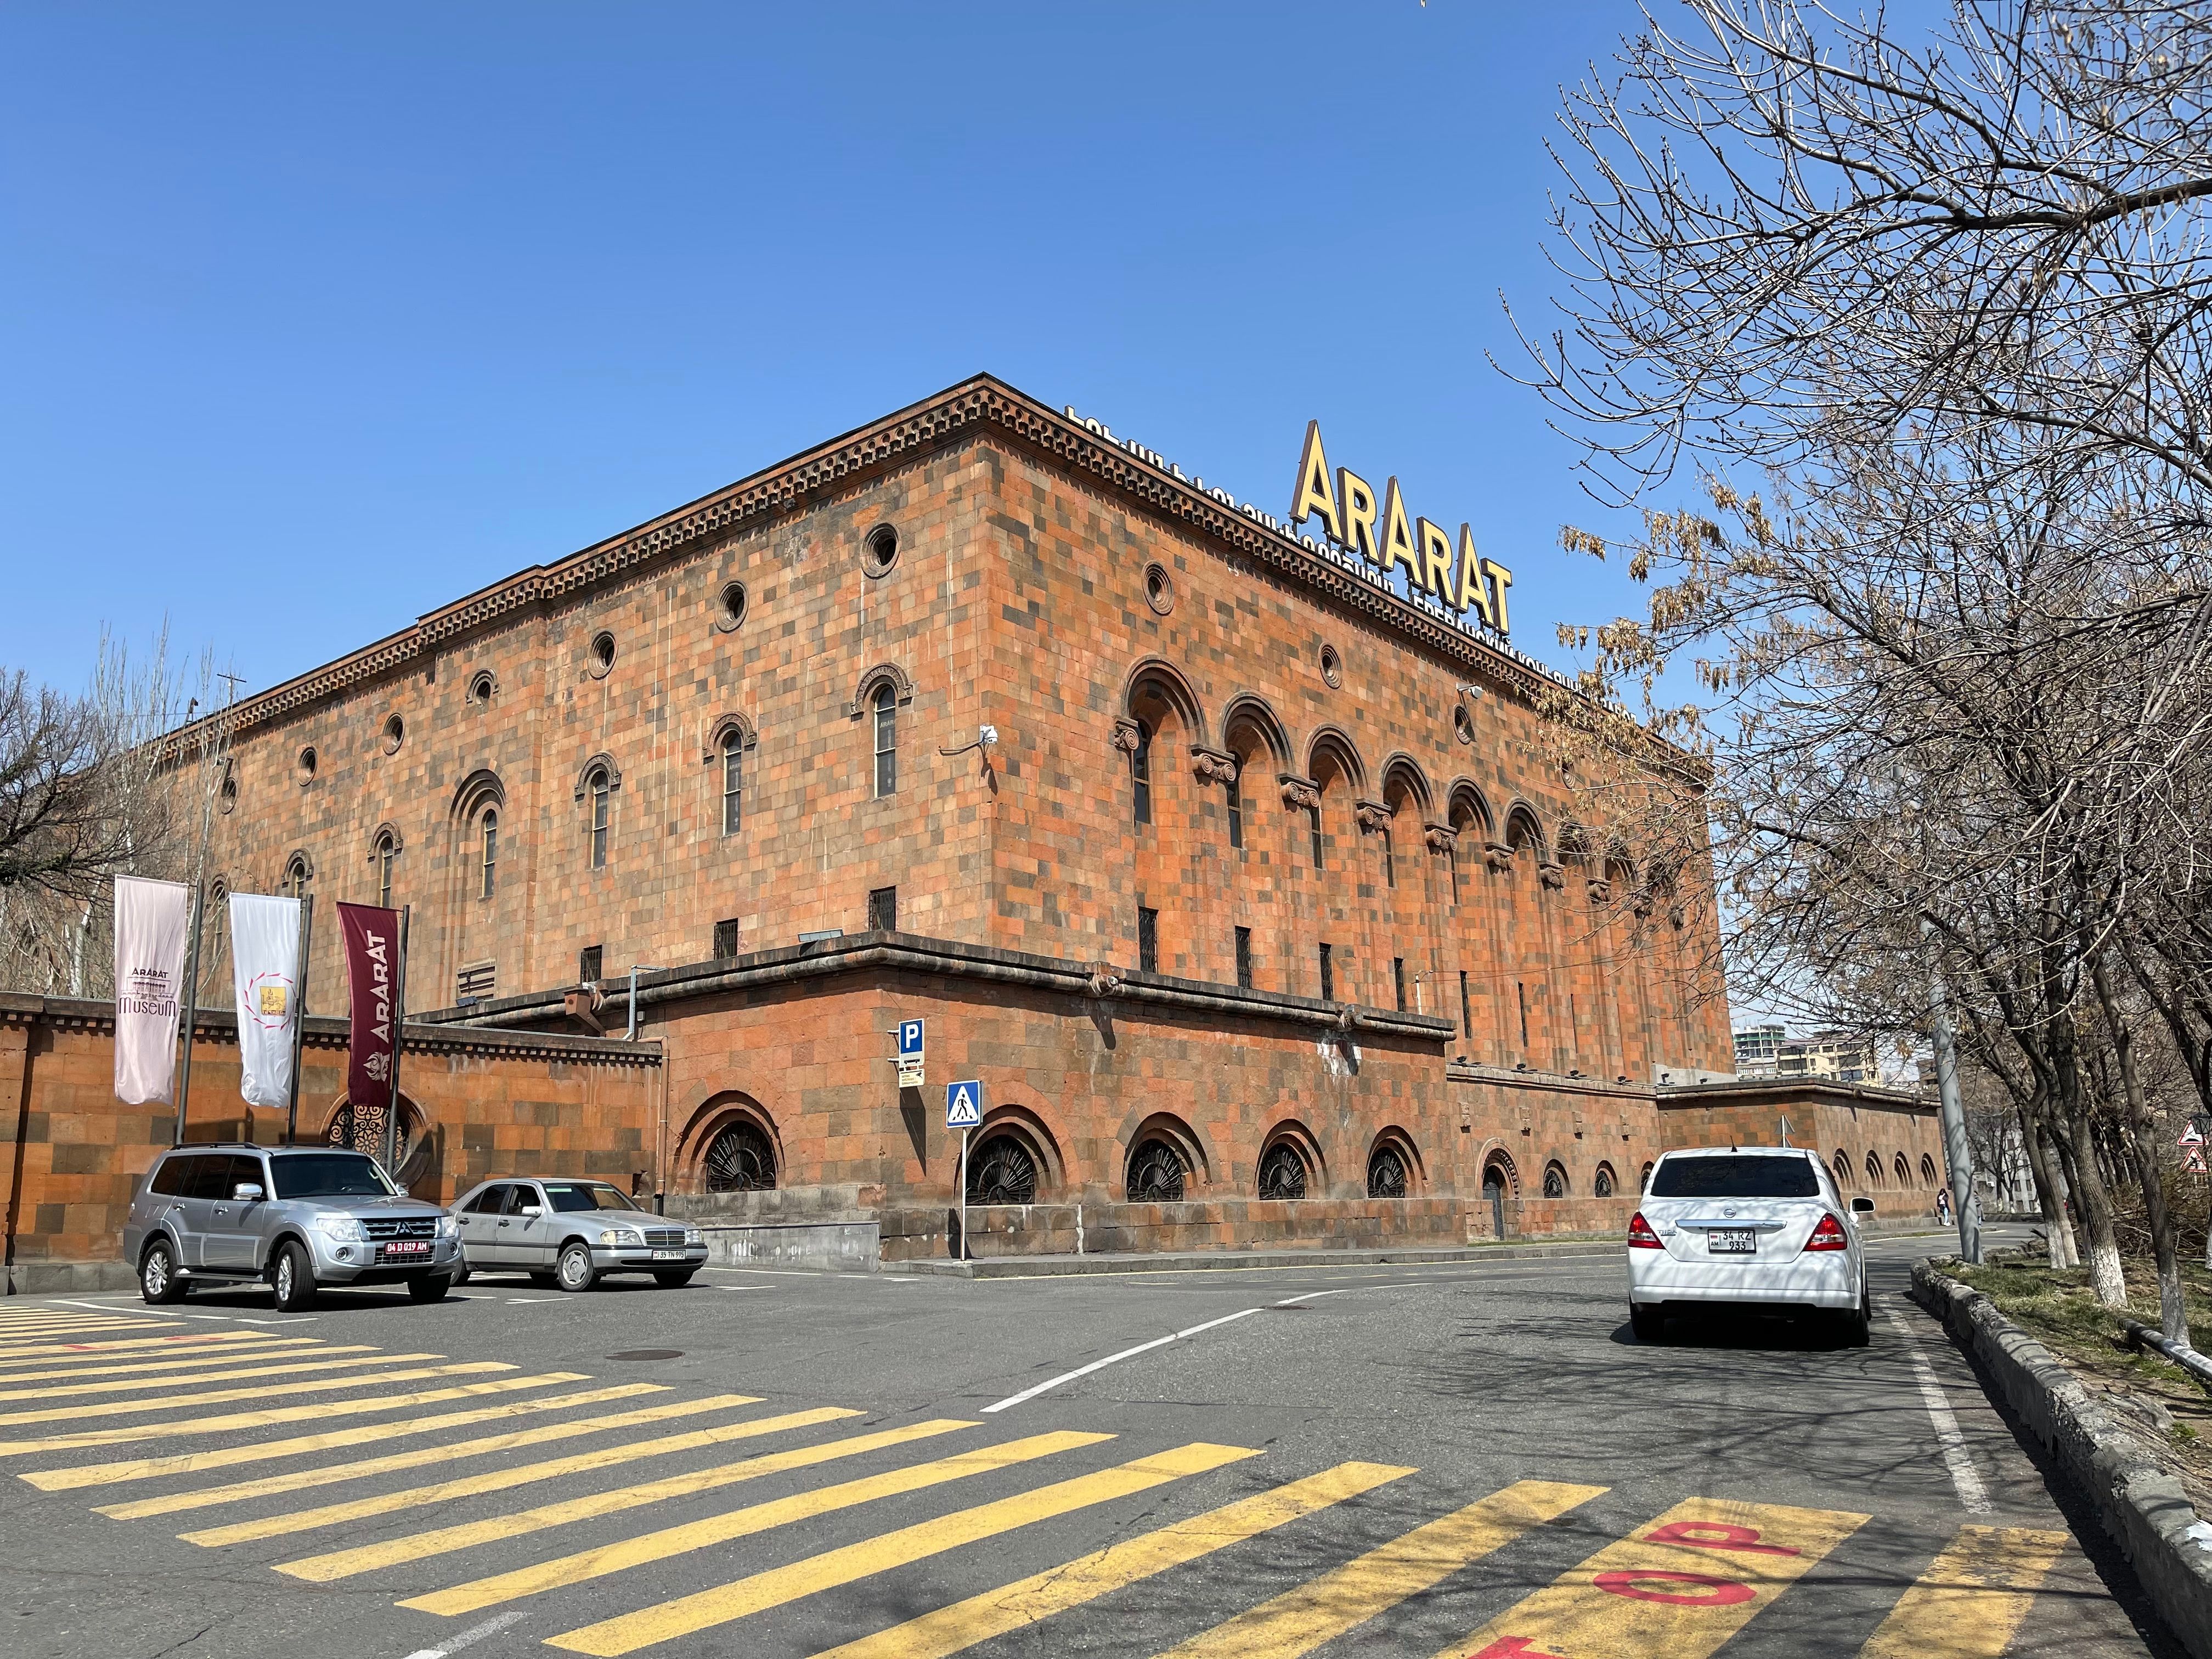
2. Eastern Europe, the Balkans, the Caucasus and the Middle East: Geopolitical Risk
A second category of risk becomes more important as we move east and southeast from Western Europe.
These regions can offer remarkable real estate opportunities:
relatively low property prices, growing cities, tourism, international investment and, in some cases, attractive taxation.
Periods of stability can also be highly prosperous.
The problem lies elsewhere.
Parts of these regions sit at the intersection of several competing spheres of influence:
the European Union, the United States, Russia, Turkey, Iran and various regional powers.
Political and geopolitical balances may remain stable for ten, twenty or even thirty years.
And then change rapidly.
The risk of borders
Western Europe has accustomed us to thinking of national borders as virtually permanent.
That is not necessarily true everywhere.
Over recent decades, the territories stretching from Eastern Europe to the Caucasus have experienced several conflicts resulting in:
- separatist regions;
- de facto independent territories;
- partially recognised states or entities;
- changes in territorial control.
Transnistria, Abkhazia, South Ossetia and, historically, Nagorno-Karabakh illustrate different forms of these territorial or so-called “frozen” conflicts.
For real estate, this is an especially difficult type of risk
A business can sometimes relocate.
A financial portfolio can often be sold quickly.
A building stays exactly where it is.
An international property investor may therefore find that:
- the country governing the property changes;
- the currency changes;
- the legal framework changes;
- international recognition becomes uncertain;
- the banking system stops functioning normally;
- or the market for potential buyers temporarily disappears.
This does not mean investors should never consider these regions.
On the contrary, prices can sometimes be attractive precisely because geopolitical risk is already reflected in valuations.
But in these markets, one principle becomes particularly important:
Never concentrate too large a share of your wealth in a single country or geopolitical area.
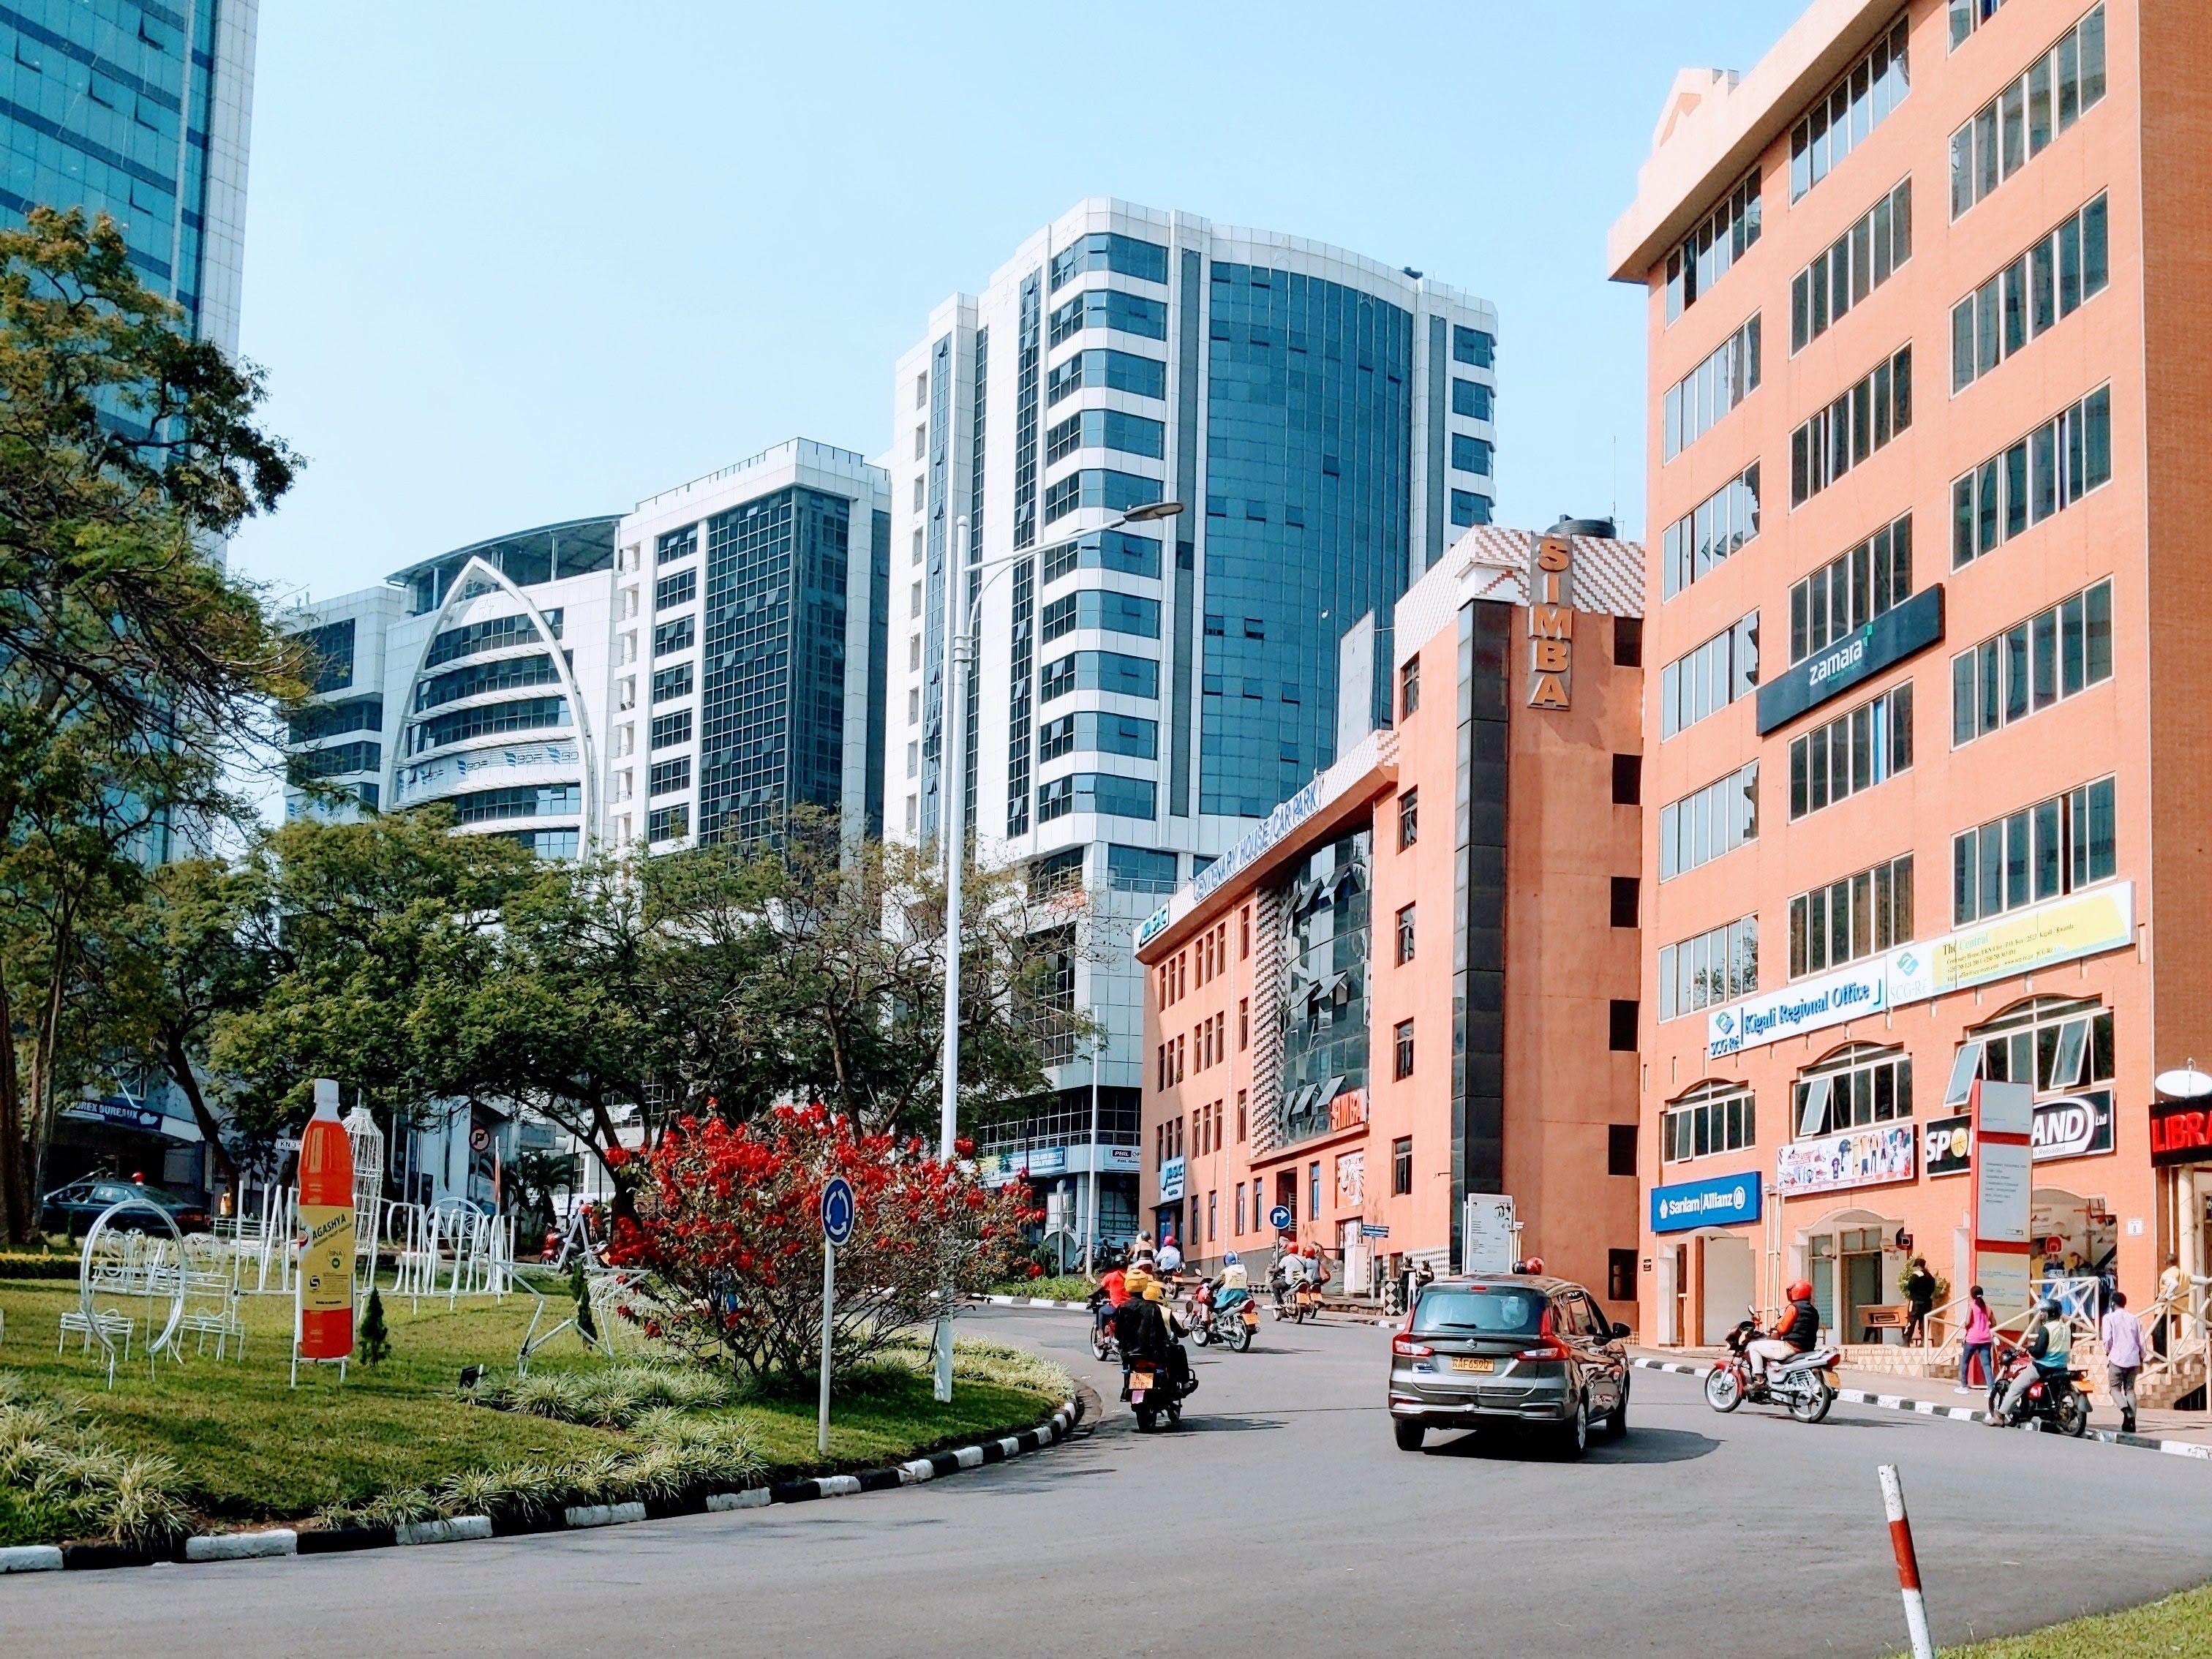
3. East Africa: Political Transition Risk
East Africa presents almost the opposite situation from many parts of Europe.
The population is growing rapidly.
The region is also experiencing significant economic growth, continued urbanisation and the gradual development of infrastructure.
Cities are expanding, new neighbourhoods are being built, and national economies are gradually increasing their industrial capacity.
For real estate, the combination of a young population, urban growth and economic development can be particularly attractive.
But it comes with a specific type of political risk.
In several countries in the region, much of the contemporary political stability has developed under leaders or political systems that have remained in place for long periods.
Sooner or later, these systems will have to go through a transition.
That transfer of power may take place in a perfectly orderly manner.
However, after decades of relative political stability, a major succession can also create a period of uncertainty involving internal rivalries, changes in economic policy, demonstrations, regulatory changes or a broader reorganisation of political institutions.
Not every East African country faces this risk in the same way.
Some already have a stronger tradition of political alternation or institutionalised presidential transitions.
Each market therefore needs to be analysed individually.
For a real estate investor, the main lesson is simple:
past stability should never be confused with guaranteed future stability.
How Can These Risks Be Managed?
The first mistake would be to search for a region with no risk. Such a place does not exist. Western Europe offers strong institutional stability but faces ageing populations, stagnation in some areas and increasing regulation of residential property. Eastern Europe, the Balkans and the Caucasus can offer attractive prices but come with greater geopolitical risk. East Africa benefits from much stronger demographic and economic trends, while carrying higher political, currency and institutional risks.
The best protection is therefore to avoid concentration. A portfolio located entirely in one country depends on a single tax system, one currency, one political environment and one property market. Several reasonably sized investments spread across different regions can reduce the impact of a problem affecting one particular market. Diversification should also take place within regions: neighbouring countries, different cities and even different neighbourhoods can follow very different trajectories.
Geographical diversification does not replace basic investment discipline. Investors should limit the size of individual positions, verify property ownership carefully, take currency risk into account, avoid excessive leverage and always consider the future resale market before buying. The objective is not to find a country that is “risk-free”, but to gradually build a portfolio that never depends entirely on a single market.
Diversifying properties is useful. Diversifying countries can be just as important.
This article presents a general discussion of geographical diversification and real estate risk. It does not constitute personalised financial, legal or tax advice. Any international property investment should be assessed individually, taking into account the market, the specific property, local law, taxation and the investor’s personal circumstances.
Would you like to know more? Contact us at +41 79 525 71 35.


 La Ville Nouvelle, Atelier d'Architectes

Laisser un commentaire